Plan Prevision Asegurado (PPA): How Spain’s Retirement Savings Insurance Works
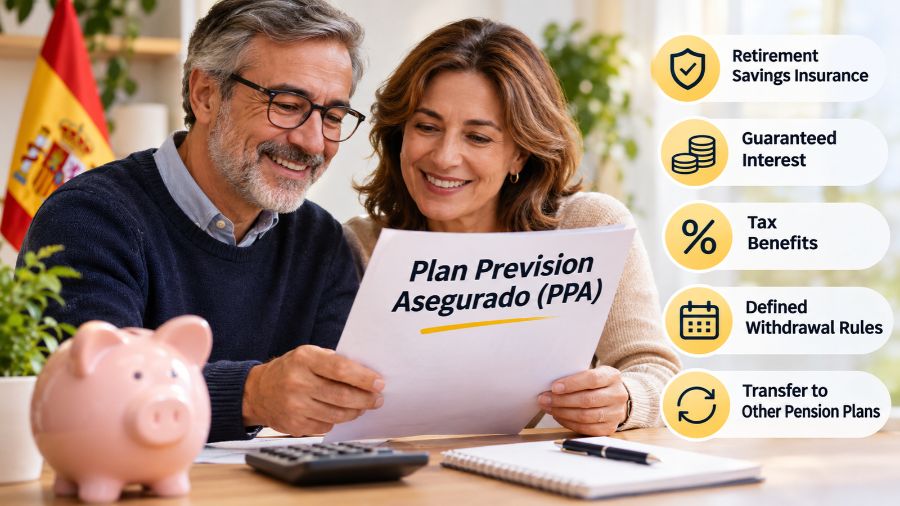
Plan Prevision Asegurado (PPA) is a Spanish retirement savings insurance product designed to help individuals build financial security for retirement while benefiting from specific tax advantages. Unlike ordinary savings accounts or investment funds, a PPA combines insurance-based guarantees with long-term pension planning. Understanding how it works, who can benefit, its tax treatment, withdrawal conditions, and potential limitations can help Spanish residents decide whether it fits their retirement strategy.
What Is a Plan Prevision Asegurado?
A Plan de Previsión Asegurado, commonly abbreviated as PPA, is a long-term retirement savings contract offered by an insurance company in Spain. It is designed to help individuals accumulate money for retirement through regular or occasional contributions. Spanish legislation establishes specific requirements for these contracts, including a guaranteed interest element, actuarial techniques, and retirement as the principal insured contingency. A PPA is therefore not simply a conventional life insurance policy or an ordinary savings account. It is a regulated retirement provision product with a specific financial and tax framework under Spain’s Personal Income Tax Law.
How Does a Plan Prevision Asegurado Work?
A PPA works by allowing an individual to contribute money to an insurance-based retirement arrangement over an extended period. The insurance company manages the accumulated mathematical reserve according to the contractual terms and applicable regulations. The policyholder builds retirement rights through contributions and the applicable financial return. When a qualifying retirement contingency occurs, the accumulated entitlement can be received according to the permitted benefit arrangements. Unlike a standard savings account, the money is generally not freely accessible whenever the policyholder wants it. The product is intended to support long-term financial planning rather than short-term spending or emergency savings.
Contributions and Savings Accumulation
Individuals can make contributions according to the conditions established by their insurance contract. Depending on the product, contributions may be made periodically or as occasional payments. The insurer calculates the accumulated mathematical reserve using the policy’s financial and actuarial conditions. The guaranteed interest requirement provides an important distinction from products whose returns depend entirely on market performance. However, the actual return, costs, contribution flexibility, and contractual conditions can differ between providers. Prospective customers should examine the policy documentation carefully instead of assuming every PPA offers the same financial outcome.
The Role of the Insurance Company
The insurance company is responsible for issuing the contract, administering contributions, calculating the relevant mathematical reserve, and providing benefits when contractual and legal conditions are satisfied. It must comply with the regulatory requirements governing this particular type of insurance. The policy should expressly identify itself as a Plan de Previsión Asegurado. This designation is legally reserved for insurance contracts that satisfy the relevant requirements. Customers should therefore verify that a product is genuinely a PPA rather than an ordinary retirement savings or life insurance product marketed using similar terminology.
Main Features of a Spanish PPA Retirement Plan
A Plan Prevision Asegurado has several characteristics that distinguish it from other retirement savings options. Its legal structure combines insurance-based financial guarantees, restricted access to accumulated savings, and a tax framework associated with Spanish pension arrangements. These features can make it attractive to people seeking predictable retirement planning, although the suitability of a particular policy depends on its costs, guaranteed return, and the individual’s financial circumstances.
Guaranteed Interest
One of the defining characteristics of a PPA is its mandatory interest guarantee. Spanish legislation requires these insurance contracts to offer a guaranteed interest element and use actuarial techniques. This provides a contractual financial guarantee that distinguishes a PPA from many investment products exposed directly to market fluctuations. However, a guaranteed interest rate does not automatically mean that every PPA will deliver a high return or protect the policyholder against inflation. Customers should check the guaranteed rate, how it is calculated, applicable expenses, and whether the guarantee applies throughout the entire contract or only during specified periods.
Retirement-Focused Savings
A PPA is primarily designed to provide financial resources during retirement. Its structure encourages individuals to accumulate savings over many years instead of withdrawing contributions whenever they need money. Retirement is the principal contingency covered by the contract, although Spanish regulations also recognize other qualifying circumstances, including certain forms of permanent disability, death, and severe dependency. The precise benefits and eligible recipients depend on the applicable legislation and policy conditions.
Transferability Between Eligible Plans
Another useful feature is the possibility of transferring accumulated mathematical reserves to another eligible retirement savings arrangement. Under the applicable Spanish framework, policyholders can generally move their PPA rights to another PPA or qualifying individual or associated pension plan. This can provide flexibility when customers find a more suitable product, better contractual conditions, or a different insurance provider. However, transfers must follow the applicable procedures, and restrictions may apply after a qualifying contingency has occurred.
Tax Benefits of a Plan Prevision Asegurado in Spain
Tax treatment is one of the main reasons individuals consider a PPA. Under Spain’s Personal Income Tax Law, qualifying contributions can reduce an individual’s general taxable income base, subject to statutory limits. This means that eligible taxpayers may reduce the amount of income subject to taxation in the relevant tax year. However, this is a tax reduction rather than a direct cash refund or an automatic tax exemption. The actual benefit depends on the taxpayer’s income, applicable marginal tax rate, contribution amount, and available annual limits. Spanish tax rules also determine how benefits are taxed when the money is eventually received.
Annual Contribution and Deduction Limits
The general annual limit for reductions relating to qualifying individual pension and retirement provision contributions is €1,500, subject to the additional requirement that the reduction cannot exceed 30% of the individual’s net employment and business income. Additional limits can apply to qualifying employer contributions and certain employment-related retirement arrangements. These limits are shared across relevant pension provision products rather than being a separate allowance exclusively for every PPA. Taxpayers should check the rules applicable to the particular tax year before making contributions, especially if they also contribute to other pension arrangements.
How PPA Tax Savings Work
The potential tax advantage comes from reducing the general taxable income base in the year eligible contributions are made. For example, an individual who contributes €1,000 to a qualifying PPA may be able to reduce their taxable base by that amount if they have sufficient eligible income and available contribution allowance. The actual tax saving depends on their applicable tax rate and personal circumstances. When the accumulated retirement benefit is eventually received, it is generally treated as employment income for Spanish personal income tax purposes. Consequently, the product provides a tax deferral mechanism rather than making the accumulated savings permanently tax-free.
When Can You Withdraw Money From a PPA?
A PPA is not designed to provide unrestricted access to savings. Its withdrawal rules follow the framework applicable to Spanish pension arrangements, meaning that money is generally available when a legally recognized contingency or qualifying early-access circumstance occurs. This restriction is important because customers who need immediate access to their savings may find a PPA unsuitable. Before signing a contract, individuals should understand the permitted withdrawal situations, documentation requirements, and potential tax consequences of receiving benefits.
Retirement
Retirement is the principal event that allows a policyholder to receive accumulated PPA benefits. Once the relevant retirement conditions are satisfied, the individual can access their entitlement according to the applicable legal framework and contractual arrangements. Depending on the available options, benefits may be received as a lump sum, periodic payments, or a combination where permitted. Choosing how to receive the money can influence the individual’s tax position, so retirement planning should consider both the payment structure and expected income in retirement.
Permanent Disability
Qualifying permanent disability can also allow access to accumulated PPA savings. Spanish pension legislation recognizes specific disability circumstances, including total and permanent incapacity for the usual profession, absolute permanent incapacity for all work, and severe disability. The relevant legal classification and supporting documentation are important when determining eligibility. A policyholder should consult the insurer and applicable regulations to establish whether their particular circumstances meet the required conditions.
Serious Illness and Long-Term Unemployment
Spanish regulations provide certain early-access provisions for circumstances such as serious illness and long-term unemployment. These provisions are intended to help individuals facing significant financial or personal difficulties. However, eligibility is not automatic simply because someone becomes unemployed or experiences a medical problem. Specific legal requirements, supporting evidence, and applicable conditions must be satisfied before funds can be accessed.
Contributions Held for Ten Years
Spanish legislation also provides an early-access mechanism for qualifying pension savings linked to contributions that have been held for at least ten years. This provision can apply to PPA arrangements under the relevant pension regulations. The availability of this option depends on the dates of contributions and the applicable transitional and legal provisions. It should not be confused with unrestricted access to the entire policy whenever the customer chooses.
Advantages of a Plan Prevision Asegurado
A PPA can be useful for people who want a structured retirement savings arrangement supported by an insurance contract. Its guaranteed interest requirement offers a degree of contractual predictability, while its tax treatment can make eligible contributions attractive for individuals who currently pay income tax in Spain. The ability to transfer accumulated rights to another qualifying arrangement can also help customers adapt their retirement strategy over time. Furthermore, the legal framework provides specific protections and access conditions for accumulated rights. Nevertheless, these advantages are most relevant to people who can commit their savings for the long term and do not depend on immediate access to their money.
Disadvantages and Risks of PPA Insurance
Despite its potential benefits, a PPA is not suitable for every investor. Limited liquidity is one of its most important disadvantages because withdrawals are restricted to legally recognized circumstances. Its guaranteed interest may also be relatively modest compared with returns that some market-linked investments could potentially achieve over longer periods. Inflation can reduce the purchasing power of accumulated savings, even when the nominal value grows. Insurance fees, administrative expenses, contractual restrictions, and the tax treatment of eventual withdrawals can also affect the final outcome. Customers should evaluate the complete policy rather than focusing only on its advertised guaranteed interest rate or tax benefits.
PPA vs Traditional Pension Plans in Spain
A Plan Prevision Asegurado and an individual pension plan are both designed to support retirement savings, and they share much of the same financial and tax framework. However, their legal structures are different. A PPA is an insurance contract issued by an insurance company, whereas a conventional pension plan is an investment-based pension arrangement managed under pension fund regulations. A PPA must provide a guaranteed interest element, while a traditional pension plan’s investment returns depend on its portfolio and market performance. Neither product is automatically better. Individuals seeking contractual interest guarantees may prefer investigating PPAs, while those comfortable with investment risk may consider pension plans with different investment strategies.
Who Should Consider a Plan Prevision Asegurado?
A PPA may be worth considering for Spanish taxpayers who want to build retirement savings, value contractual interest guarantees, and can accept restrictions on withdrawing their money. It may also appeal to individuals who prefer an insurance-based arrangement rather than managing a market-exposed investment portfolio directly. However, people with unstable income, significant short-term financial commitments, or insufficient emergency savings should carefully assess whether locking money away is appropriate. Tax benefits alone are not enough to justify purchasing a product. The decision should reflect retirement goals, existing pension arrangements, income, investment preferences, and the overall cost of the policy.
How to Choose the Right PPA Provider
Choosing a PPA requires more than comparing the advertised interest rate. Customers should review the insurer’s financial strength, contractual guarantees, policy expenses, transfer conditions, contribution flexibility, and benefit payment options. They should also understand whether the quoted return is guaranteed for the full duration or subject to periodic revisions. Reading the official policy documentation is particularly important because two products carrying the same PPA designation can have different financial conditions. Before committing, individuals should compare several offers and consider obtaining independent financial or tax advice. A product that offers a slightly higher guaranteed rate may not necessarily provide the best overall value once costs and restrictions are considered.
Conclusion
A Plan Prevision Asegurado (PPA) is a regulated Spanish retirement savings insurance product that combines guaranteed interest requirements, long-term financial planning, and potential income tax advantages. It can provide a structured approach to retirement preparation for individuals who value contractual guarantees and accept limited access to their savings. However, contribution limits, withdrawal restrictions, inflation, policy expenses, and taxation of retirement benefits must all be considered. Understanding these factors and comparing different insurance providers can help individuals determine whether a PPA is an appropriate part of their long-term financial strategy.
FAQs
1. What does Plan Prevision Asegurado mean?
Plan Prevision Asegurado means Assured Retirement Provision Plan, a Spanish insurance-based savings product designed to help individuals accumulate money for retirement.
2. Is a Plan Prevision Asegurado the same as a pension plan?
No. A PPA is an insurance contract, whereas a conventional pension plan is an investment-based retirement arrangement governed by separate regulations.
3. Are contributions to a PPA tax deductible in Spain?
Eligible contributions can reduce Spain’s general taxable income base, subject to annual contribution limits, income requirements, and applicable tax legislation.
4. Can I withdraw money from my PPA before retirement?
Yes, but only under legally permitted circumstances, including qualifying serious illness, long-term unemployment, disability, or eligible contributions held for ten years.
5. Does a Plan Prevision Asegurado guarantee investment returns?
Spanish law requires PPAs to offer guaranteed interest, but actual returns depend on contractual terms, expenses, and the applicable interest guarantee.
6. Who should consider purchasing a PPA?
Spanish taxpayers seeking structured retirement savings, contractual interest guarantees, and potential tax advantages may consider a PPA after evaluating liquidity restrictions and costs.
More read: Foodie Co